
You have decided it might be time for a change. Maybe you need more space, want to downsize, or are preparing for a move to a different neighborhood. Whatever your reason, there is one important question to answer before moving forward: What should you do with your current home?
For many homeowners, selling is the natural choice. But when properties spend more time on the market than expected, the idea of keeping the house and collecting rental income can become increasingly appealing.
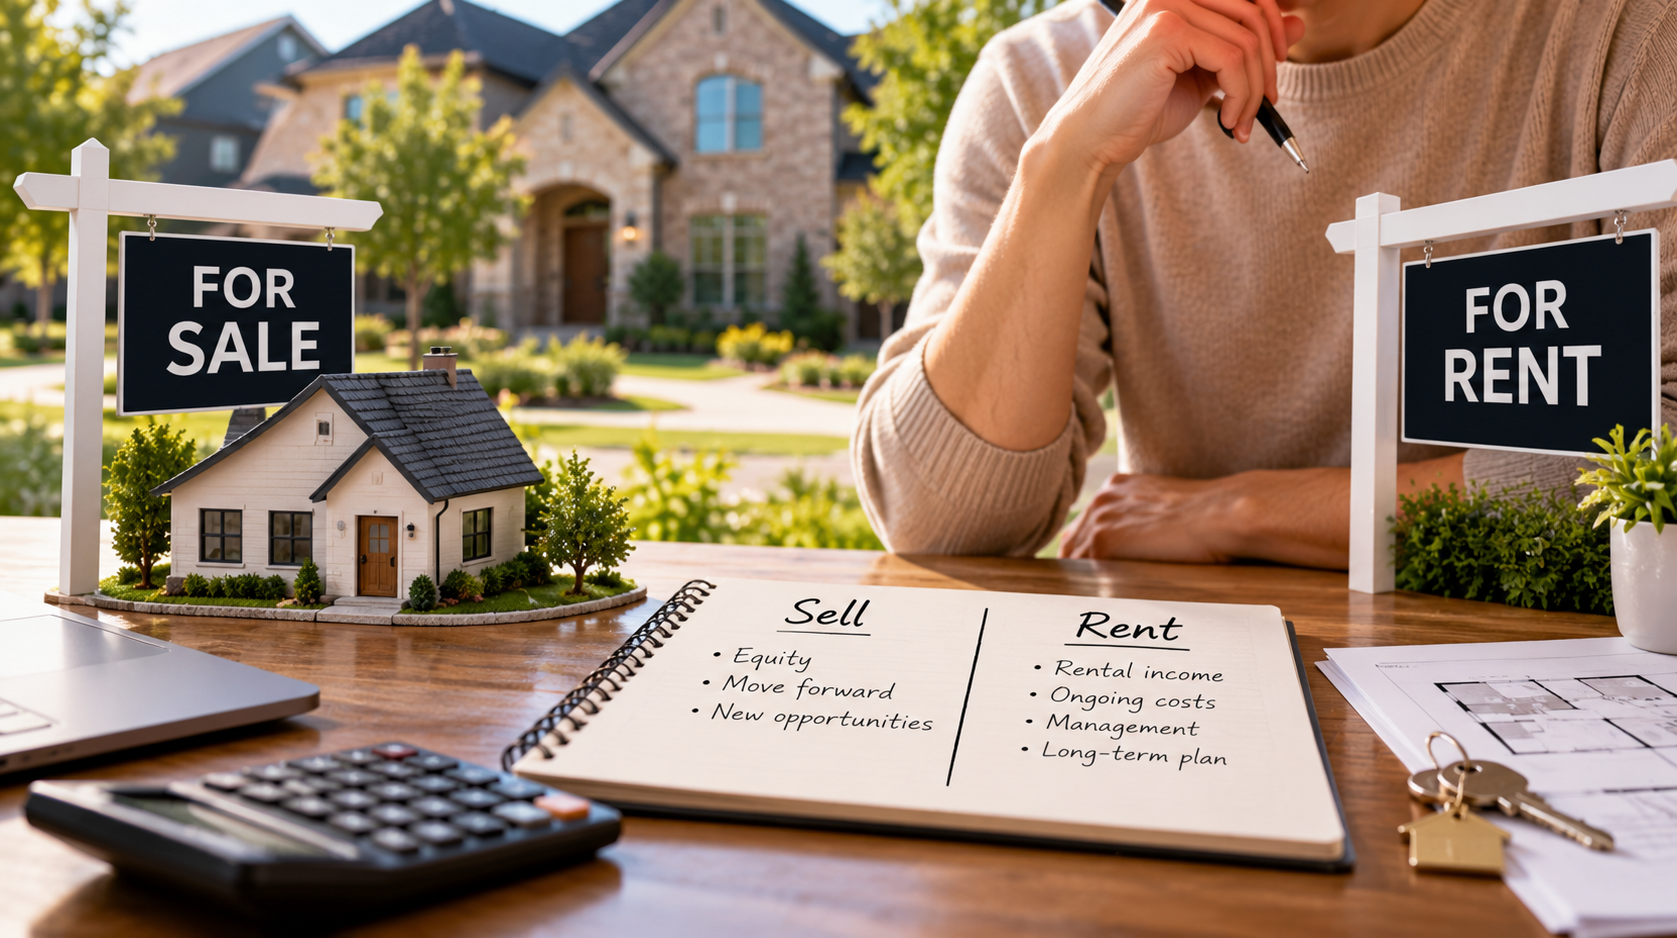
At first glance, both options have their advantages. Selling gives you access to your equity and allows you to move forward without ongoing property responsibilities. Renting, meanwhile, offers the possibility of recurring income while retaining ownership of an asset.
The better choice depends on your financial situation, your future plans, and what is happening in your local housing market.
Why More Homeowners Are Exploring the Rental Option
Not every homeowner who becomes a landlord originally planned to own rental property.
Sometimes, the decision happens after a home has already been listed for sale.
A property might attract fewer offers than anticipated. Buyers may negotiate more aggressively, or the asking price may no longer align with what the market is willing to support.
Rather than adjusting their selling strategy, some homeowners decide to withdraw their listings and offer their properties for rent.
Research from Parcl indicates that approximately 9% of available rental homes had previously been advertised for sale.
Kara Ng, Senior Economist at Zillow, describes the changing dynamics behind these decisions:
“Bargaining power is tilting toward buyers and homes are taking longer to sell, making renting out a property one way to buy time rather than compete aggressively on price.”
This trend highlights something worth remembering: A home that does not sell within the expected timeframe is not necessarily a home that cannot sell.
Sometimes, the issue is simply a mismatch between the seller’s expectations and current buyer behavior.
Pricing, presentation, competition, and marketing all influence how quickly a property attracts serious interest.
The prevalence of homeowners switching from selling to renting also varies significantly across the country.

In Sherman, Texas, approximately 17.4% of rental listings fall into this category, while Houston follows closely at 16.9%. Other markets, including Des Moines, Iowa, and Bloomington, Indiana, report considerably smaller percentages.
These differences illustrate why national housing headlines rarely tell the entire story.
For homeowners in North Texas, understanding neighborhood specific conditions is especially important. The experience of selling a property in McKinney may differ from selling in another community, even within the same metropolitan area.
Before changing your plans, consider reviewing recent comparable sales, current inventory, competing listings, and buyer activity with a knowledgeable local real estate professional.
You may discover that a different pricing or marketing approach could make selling more achievable than you initially thought.
Rental Income Is Only Part of the Financial Picture
The prospect of receiving a monthly rent payment sounds attractive, particularly if you have built substantial equity in your home.
However, the amount a tenant pays each month is not the same as the amount you actually earn.
Owning rental property involves financial commitments that continue regardless of whether the property is occupied.
Mortgage payments, property taxes, insurance, repairs, and routine upkeep all need to be accounted for. Depending on the property’s age and condition, major replacements such as roofing, HVAC equipment, or plumbing can also create significant expenses.
Before committing to the rental route, calculate what your property would realistically generate after these obligations.
A home that produces positive monthly cash flow may be worth holding. On the other hand, if expenses consume most of the rental income, the financial benefit may be smaller than expected.
And the financial considerations are only one part of the equation.
Becoming a Landlord Means Taking On New Responsibilities
Keeping your home as a rental changes your role from homeowner to housing provider.
That comes with legal, financial, and practical responsibilities that should not be underestimated.
Invest West Management explains the importance of understanding those obligations:
“Even if you never intended to become a landlord, the law still sees you as one — and you must meet all legal obligations that come with that role. This often includes registering the tenancy, providing tenants with certain disclosures, and ensuring the property meets safety standards.”
Requirements vary by location, but landlords generally need to understand applicable housing laws, lease agreements, security deposit rules, maintenance standards, and tenant protections.
In Texas, owners should also become familiar with state landlord and tenant laws and any applicable local requirements.
Beyond legal compliance, there is the everyday work of managing a property.
Tenants may need assistance with maintenance issues, appliances can fail unexpectedly, and repairs sometimes require immediate attention.
There is also the possibility of late payments, property damage, and periods when the home sits vacant.
You can hire a property management company to handle many of these tasks, but professional assistance adds another expense to your budget.
According to Bankrate, several common costs deserve attention:
- Landlord insurance: Coverage for rental properties can cost approximately 25% more than a typical homeowners insurance policy.
- Property management: Professional management services may charge around 10% of monthly rental income.
- Vacancy periods: Mortgage payments and other ownership expenses continue even when there is no tenant paying rent.
These figures are general estimates, and actual costs can vary depending on the property, location, and services required.
The key is to evaluate rental ownership as an ongoing financial commitment rather than simply an additional source of monthly income.
Selling Could Give You More Flexibility for Your Next Chapter
There are situations where retaining a property makes sense, especially if the home generates dependable income and supports your long term investment goals.
But there are also compelling reasons to sell.
Selling can release the equity you have accumulated, which may help fund your next home purchase, reduce debt, strengthen your savings, or support another financial priority.
It also eliminates the ongoing responsibilities associated with maintaining a property you no longer intend to occupy.
For homeowners planning to purchase another home, this distinction can be particularly important.
Keeping your existing property may affect your available down payment, debt obligations, and mortgage qualification. Selling could provide greater financial flexibility and simplify the transition.
There may also be tax implications to consider. Depending on your circumstances, selling a qualifying primary residence may provide access to certain capital gains exclusions, while converting the property into a rental can introduce additional tax considerations.
A qualified tax professional can help you understand how those rules apply to your situation.
Before You Decide, Compare the Numbers and Your Priorities
Instead of asking whether selling or renting is generally better, consider which option better supports what you want to accomplish.
Start with the financial comparison.
If you sell, estimate your likely sale price, remaining mortgage balance, transaction expenses, and the equity you would receive after closing.
If you rent, determine a realistic monthly rental rate and subtract mortgage payments, property taxes, insurance, maintenance reserves, management fees, and potential vacancy costs.
Then consider the personal side of the decision.
Do you want to manage a rental property for several years? Would you be comfortable paying for unexpected repairs? Is keeping the home consistent with your financial goals?
Or would you prefer to sell, simplify your responsibilities, and use your equity elsewhere?
Neither choice is automatically better.
What matters is understanding the tradeoffs before making a commitment.
A Well Planned Sale Can Still Be the Right Move
If selling was your original goal, a changing market does not necessarily mean you need to abandon that plan.
Today’s buyers may have more choices and higher expectations, which makes thoughtful preparation and competitive pricing especially important.
Homes that are presented well, marketed effectively, and priced according to current conditions can still attract qualified buyers.
A local real estate professional can help you evaluate comparable properties, identify what buyers are responding to, and develop a strategy that positions your home competitively.
Sometimes, the difference between a listing that struggles and one that attracts attention comes down to making the right adjustments early.
Final Thoughts
Your home is more than a place to live. It is also a significant financial asset, and deciding what to do with it deserves careful consideration.
Renting may offer long term investment opportunities, while selling can provide immediate access to equity and greater freedom to pursue your next move.
The right decision depends on your numbers, your comfort with responsibility, and your plans for the future.
Thinking about selling or renting your home in North Texas? Let’s review your property’s current market value, potential rental income, and available options so you can move forward with a plan that makes sense for you.
Selling Soon | Vesta Schneider Real Estate
Looking For a New Home | Vesta Schneider Real Estate